Key Takeaways
- The average used car now costs around 25,000 dollars, well below new car prices near 49,000 dollars.
- Average used car loan rates sit near 11.43 percent, though your credit score changes this significantly.
- Over 36 million used vehicles sell in the United States every year.
- A pre-purchase inspection catches mechanical problems that a vehicle history report alone cannot reveal.
- Credit score differences can shift your interest rate by more than 15 percentage points.
- A solid used car buying guide combines inspection, pricing research, and financing prep before you negotiate.
Buying a used car still saves real money compared to buying new. However, that savings only holds up if you inspect, price, and finance the deal correctly. As the automotive specialists at VehicleTradeUS.com often warn, skipping any one of these steps can easily cost buyers thousands down the road. This used car buying guide walks through each stage clearly, so you can shop with real confidence.
Understanding Today’s Used Car Market
Prices and financing costs both shape what a smart used car purchase looks like right now. Ignoring current market conditions often leads buyers to overpay or accept bad loan terms.
As of early 2026, the average used vehicle listing price sits around 25,000 to 25,400 dollars. Compare that to new vehicles, which average close to 49,000 dollars during the same period. That roughly 24,000 dollar gap explains why used cars remain the smarter financial choice for most buyers.
However, used prices have not returned to pre-pandemic levels either. Automakers built millions fewer vehicles during 2021 and 2022, and many of those missing cars will never reach used lots. This shortage keeps supply tighter than buyers might expect, even years later.
Body style trends matter too. More than half of all vehicles sold today are SUVs or crossovers, up sharply from just a few years ago. This shift affects which models hold value best and which ones sit longer on dealer lots. Additionally, buyers now keep their vehicles for six to eight years on average, which reduces the flow of well-maintained trade-ins entering the used market.
Understanding these dynamics before you shop helps set realistic expectations. Therefore, walk into any deal knowing prices remain elevated, supply stays limited, and patience often pays off during negotiations.

How to Inspect a Used Car Properly
Skipping inspection steps ranks among the costliest mistakes a used car buyer can make. A car that looks clean on the surface can hide expensive mechanical problems underneath.
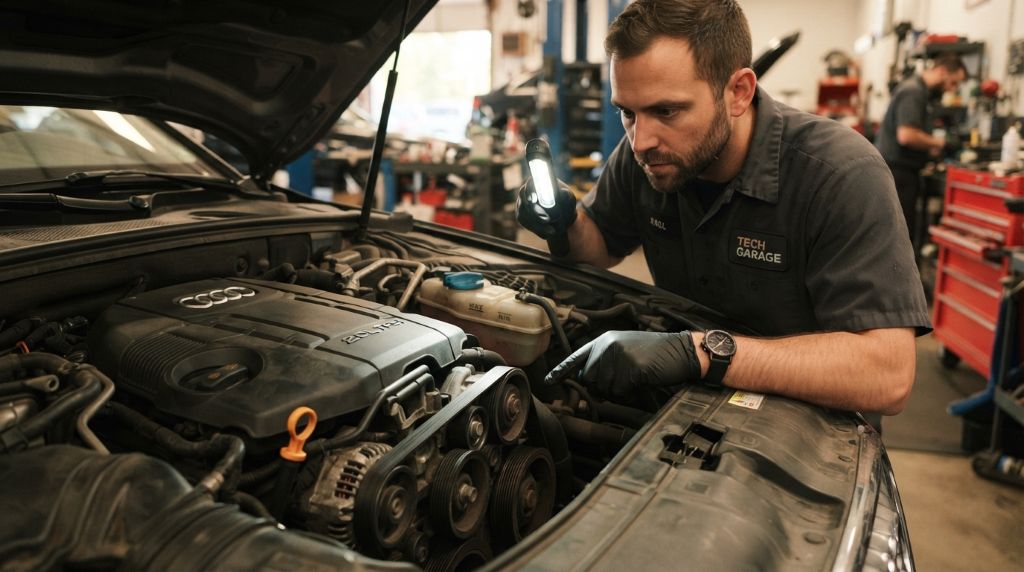
Start with a vehicle history report before you even schedule a viewing. A CarFax report can reveal accident history, airbag deployment, and structural damage tied to the vehicle’s identification number. If a report shows severe collision damage, proceed carefully and ask for detailed repair documentation. However, a clean report does not guarantee a mechanically sound car, since not every repair shop submits data to these services.
This is exactly why a pre-purchase inspection matters just as much as the history report. A professional mechanic evaluates the car’s actual current condition, not just its documented past. Given that over 36 million used vehicles sell across the country each year, competition for good deals stays fierce, making inspection even more important before committing.
Prioritize inspections especially in these situations:
- Buying from a private seller with no dealer warranty backing the sale.
- Vehicles with mileage above 75,000 to 100,000 miles, where wear items become likely.
- Cars missing full maintenance records from previous owners.
- Any vehicle with a history report showing prior accident damage.
A qualified mechanic checks brakes, suspension, fluid levels, and signs of hidden frame damage. This step typically costs far less than the repairs it can help you avoid. Therefore, never skip this step to save a small inspection fee upfront.
Pricing the Vehicle Fairly
Knowing a fair price protects you from overpaying, even in a tight market. Pricing research takes real effort, but it pays off directly during negotiation.
Start by comparing similar listings across multiple platforms, not just one dealership’s inventory. Look at vehicles with matching year, mileage, trim level, and condition for an accurate comparison. Wholesale pricing indexes also help, since they track how quickly used vehicle values are rising or falling nationally.
Consider total ownership cost, not just the sticker price alone. A slightly cheaper car with poor fuel economy or high insurance costs can cost more over time. Additionally, factor in likely maintenance costs based on the vehicle’s age and mileage before finalizing your decision.
Timing plays a role too. Dealerships often become more flexible near the end of a sales month or quarter, when they push to hit targets. Shopping during slower demand periods, rather than peak buying seasons, can also improve your negotiating position.
Finally, always separate the vehicle price from financing terms during your research. A dealer might offer a lower price while quietly building extra profit into the loan itself. Therefore, keep these two numbers separate until you understand both clearly. This approach protects you from deals that look good on paper but cost more overall.
Financing Without Overpaying
Financing costs shape your total expense as much as the car’s purchase price. Understanding current rates helps you avoid accepting a bad deal out of convenience.
The average used car loan rate currently sits around 11.43 percent, based on recent Experian data. However, your actual rate depends heavily on credit score. Buyers with super prime credit scores above 781 often see rates near 6.3 percent, while those with deep subprime scores can face rates above 21 percent. That gap shows exactly why checking your credit before shopping matters enormously.
Getting pre-approved through a bank or credit union before visiting a dealership gives you real negotiating leverage. You walk in already knowing your baseline rate, which makes it harder for a dealer to quietly inflate financing costs. Additionally, comparing at least two or three loan offers helps confirm you are getting a competitive rate.
Loan term length affects your total cost significantly too. A longer term lowers your monthly payment but increases total interest paid over the life of the loan. Therefore, choose the shortest term you can comfortably afford, rather than automatically picking the lowest monthly payment.
Watch for add-on products dealers frequently push during financing paperwork. Extended warranties and gap insurance sometimes offer real value, but they also inflate your loan balance if bundled without careful review.
Negotiating With Confidence
Negotiation intimidates many buyers, yet it remains one of the most valuable skills in the entire car-buying process. Preparation, not aggression, wins most negotiations.
Walk in already knowing three numbers clearly: your researched fair price, your maximum budget, and your pre-approved loan rate. This preparation prevents a salesperson from steering the conversation toward numbers that favor the dealership instead.
Use any issues found during inspection as leverage during price discussions. A vehicle history report showing prior accident damage, or an inspection revealing worn brakes, gives you legitimate grounds to negotiate down. Present these findings calmly and directly, rather than as complaints.
Stay willing to walk away if the numbers do not work. Dealerships often improve their offer once they sense a buyer is genuinely prepared to leave. Additionally, negotiate the vehicle price and financing terms separately, since combining them makes it harder to track your actual savings.
Consider these practical negotiation habits:
- Bring printed comparisons of similar vehicle listings to support your target price.
- Ask directly about any known issues rather than waiting for the dealer to disclose them.
- Request time to review paperwork rather than signing under pressure.
- Confirm the out-the-door price, including taxes and fees, before agreeing to anything.
Therefore, confidence in negotiation comes directly from preparation done beforehand, not from natural charisma alone.
Final Thoughts
A smart used car purchase depends on careful work done before you ever sign paperwork. Inspection catches hidden problems, fair pricing protects your budget, and smart financing prevents unnecessary interest costs. Before moving forward, it is also worth reviewing a vehicle history report checklist to verify important details such as previous accidents, ownership records, mileage, and reported damage. Skipping any single step in this used car buying guide increases your risk of an expensive mistake.
Take your time through each stage, even when a deal feels urgent or exciting. The buyers who research, inspect, and negotiate carefully consistently end up with better vehicles at fairer prices. That extra effort pays off for years of ownership ahead.
Have you gone through the used car buying process recently? Share your experience in the comments, and pass this guide along to someone starting their own car search.
How much should I budget for a pre-purchase inspection?
Most independent mechanics charge a modest flat fee, far less than the cost of repairing a hidden mechanical issue later.
Is a clean CarFax report enough to skip a mechanical inspection?
No. A history report shows documented past events, but only a hands-on inspection confirms the car’s current condition.
What credit score gets the best used car loan rate?
Scores above 781 typically qualify for the lowest available rates, often near 6 percent APR in the current market.
Should I get pre-approved for financing before visiting a dealership?
Yes. Pre-approval gives you a clear baseline rate and stronger negotiating leverage once you start shopping.
Is it better to negotiate price and financing together or separately?
Separately. Keeping these numbers apart makes it easier to spot inflated financing costs hidden behind a lower sticker price.


