
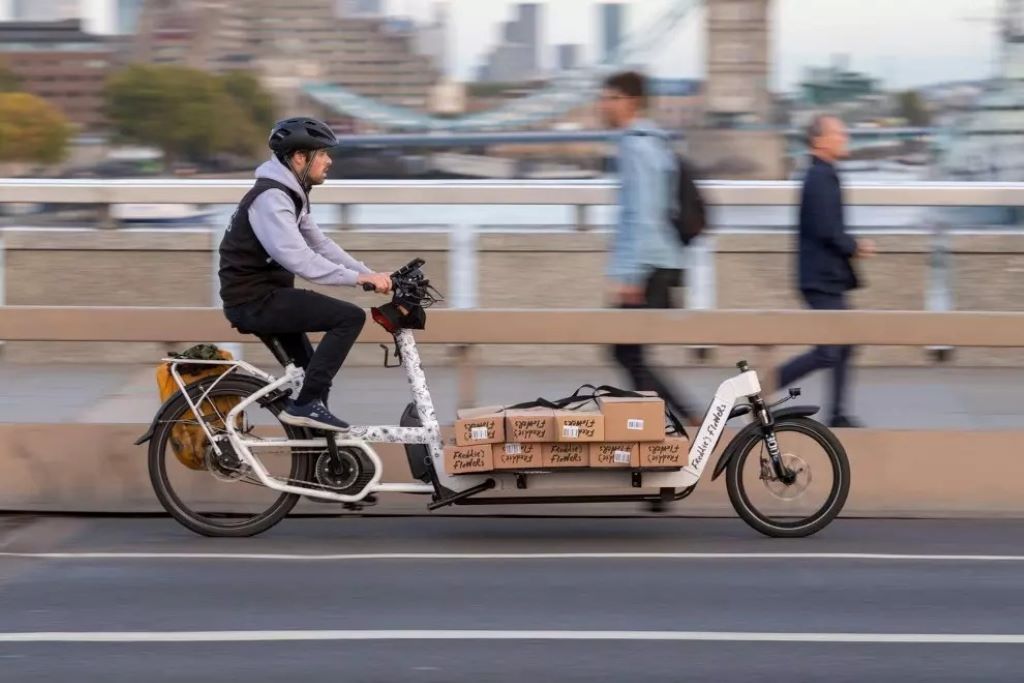
The gig economy has transformed urban delivery services, with independent couriers increasingly choosing cargo bikes for their business operations. These versatile vehicles offer eco-friendly solutions for last-mile deliveries while providing cost-effective alternatives to traditional delivery methods. However, indie couriers face unique insurance challenges that require specialized coverage options. Wanna Taxi provides comprehensive transportation insights that help modern couriers understand their insurance needs and coverage options.
Independent cargo bike couriers operate in a complex insurance landscape where personal and commercial coverage requirements often overlap. Traditional bicycle insurance may not adequately protect business operations, while commercial vehicle policies might not apply to pedal-powered transportation. Additionally, the evolving nature of delivery services creates new risks that require innovative insurance solutions.
Understanding what is modern transportation helps couriers recognize how cargo bikes fit into the broader logistics ecosystem and why specialized insurance coverage is essential. Therefore, indie couriers must navigate multiple insurance types to ensure comprehensive protection for their business assets and potential liabilities.
Understanding Cargo Bike Classifications
Pedal-Powered vs Electric-Assisted Models
Insurance companies classify cargo bikes differently based on their power systems and maximum speeds. Traditional pedal-powered cargo bikes typically fall under bicycle insurance categories with modified coverage options. However, electric-assisted cargo bikes may require additional considerations due to their higher speeds and increased complexity.
Electric cargo bikes with motors exceeding certain power thresholds might classify as mopeds or light motorcycles in some jurisdictions. This classification significantly impacts insurance requirements and coverage options. Additionally, battery-related risks create new liability considerations that traditional bicycle policies don’t address.
The distinction between pedal-assist and throttle-controlled electric systems also affects insurance classifications. Pedal-assist systems typically maintain bicycle status, while throttle-controlled bikes might require motorcycle-style coverage. Therefore, understanding your specific cargo bike type is crucial for selecting appropriate insurance protection.
Weight and Cargo Capacity Considerations
Insurance providers consider cargo bike weight limits and typical load capacities when determining coverage terms and premiums. Bikes designed for heavy freight transport face different risk profiles than those used for light package delivery. Additionally, exceeding manufacturer weight recommendations might void certain coverage provisions.
Three-wheeled cargo bikes and those with extended wheelbases present unique stability considerations that affect insurance risk assessments. These design factors influence accident likelihood and potential damage severity. However, proper training and equipment can mitigate many stability-related risks.
Cargo securement systems and weather protection features also impact insurance considerations. Bikes equipped with professional-grade cargo boxes demonstrate commitment to safe operations. Therefore, investing in quality equipment might result in lower insurance premiums and better coverage terms.
Types of Insurance Coverage for Indie Couriers
Personal vs Commercial Coverage
Independent couriers must distinguish between personal bicycle insurance and commercial coverage requirements. Personal policies typically exclude business use, leaving couriers vulnerable during work activities. However, some insurers offer hybrid policies that bridge personal and light commercial needs.
Commercial courier insurance addresses business-specific risks including cargo liability, client property protection, and third-party damage claims. These policies often include coverage for equipment theft, accident-related income loss, and legal defense costs. Additionally, commercial coverage may extend to clients’ property while in transit.
The distinction becomes crucial when filing claims, as insurers scrutinize policy terms regarding business use. Using personal coverage for commercial activities can result in claim denials and policy cancellation. Therefore, honest disclosure of business activities ensures proper coverage and claim protection.
Liability Protection Essentials
Third-party liability coverage protects couriers against claims for property damage or personal injury caused during business operations. This coverage is essential for indie couriers who interact with pedestrians, vehicles, and property owners throughout their routes. Additionally, liability protection extends to legal defense costs and settlement payments.
Public liability insurance covers incidents occurring in public spaces, while professional indemnity insurance protects against errors or omissions in service delivery. Both coverage types are important for comprehensive protection. However, policy limits and exclusions vary significantly between providers.
Product liability considerations arise when couriers transport food, medications, or other sensitive items. Temperature-sensitive cargo or time-critical deliveries create additional liability exposures that standard policies might not cover. Therefore, specialized coverage endorsements may be necessary for certain delivery types.
Equipment and Theft Protection
Cargo bikes represent significant investments that require adequate theft and damage protection. Standard homeowner’s or renter’s insurance rarely covers commercial equipment or provides sufficient coverage limits. Additionally, theft rates for cargo bikes exceed those of traditional bicycles due to their higher values.
Comprehensive equipment coverage should include replacement cost protection rather than depreciated actual cash value. This ensures that stolen or damaged bikes can be replaced with equivalent new equipment. However, depreciation schedules and coverage limits vary between policies.
GPS tracking systems and security devices might qualify for insurance discounts while providing recovery assistance if theft occurs. Some insurers require specific security measures as policy conditions. Therefore, investing in approved security systems provides dual benefits of theft deterrence and insurance savings.
Risk Assessment for Cargo Bike Couriers
Urban Environment Hazards
City riding exposes cargo bike couriers to unique risks including aggressive traffic, pedestrian conflicts, and infrastructure challenges. Bike lanes designed for standard bicycles may not accommodate cargo bike dimensions safely. Additionally, construction zones and temporary obstacles create unexpected hazards.
Weather conditions significantly impact cargo bike safety and operational efficiency. Rain, snow, and high winds affect stability and braking performance, particularly for heavily loaded bikes. However, proper equipment and training can mitigate many weather-related risks.
Parking and loading zone restrictions create operational challenges that might increase theft or damage risks. Couriers often must leave bikes unattended in less secure locations to complete deliveries. Therefore, understanding local regulations and planning secure parking strategies reduces exposure.
Client and Cargo-Specific Risks
Different types of cargo present varying risk profiles that affect insurance needs and premium calculations. Valuable electronics require higher coverage limits than standard documents or clothing. Additionally, fragile items increase the likelihood of damage claims during transport.
Food delivery creates specific liability exposures related to temperature control, contamination, and delivery timing. Late deliveries might result in spoiled food and customer complaints. However, insulated cargo compartments and temperature monitoring systems can reduce these risks.
Hazardous materials restrictions and special handling requirements create additional compliance obligations for couriers. Insurance policies might exclude coverage for prohibited items or require special endorsements. Therefore, understanding cargo restrictions prevents coverage gaps and legal issues.
Seasonal and Operational Variations
Courier activity levels fluctuate seasonally, affecting both risk exposure and insurance needs. Holiday seasons typically increase delivery volumes and traffic congestion, raising accident probability. Additionally, winter weather conditions create specific challenges for cargo bike operations.
Night and weekend operations present different risk profiles than standard business hours. Reduced visibility and different traffic patterns affect safety considerations. However, many couriers prefer off-peak hours for faster travel times and reduced congestion.
Peak delivery periods might require temporary coverage increases to accommodate higher cargo values or expanded operations. Some policies allow seasonal adjustments to avoid paying for unnecessary coverage during slower periods. Therefore, flexible coverage options provide cost-effective solutions for variable business needs.
Choosing the Right Insurance Provider
Specialized vs General Insurers
Insurance companies specializing in bicycle or courier coverage often provide better understanding of industry-specific risks and needs. These providers typically offer more flexible policy terms and faster claim processing. Additionally, specialized insurers may provide risk management resources and safety training programs.
General insurance companies might offer competitive pricing but may lack expertise in cargo bike operations. Their policies might contain exclusions or limitations that don’t suit courier needs. However, established insurers often provide broader coverage options and financial stability.
Comparing coverage terms is more important than comparing premiums alone when evaluating insurance options. The cheapest policy might not provide adequate protection when claims arise. Therefore, careful policy review and professional consultation ensure appropriate coverage selection.
Policy Terms and Conditions
Understanding policy exclusions is crucial for avoiding coverage surprises during claim situations. Common exclusions include racing activities, intentional damage, and wear-and-tear issues. Additionally, territorial restrictions might limit coverage to specific geographic areas.
Deductible amounts significantly impact both premium costs and out-of-pocket expenses during claims. Higher deductibles reduce premiums but increase financial responsibility when incidents occur. However, selecting appropriate deductible levels balances affordability with financial protection.
Policy renewal terms and rate adjustment procedures affect long-term insurance costs and coverage continuity. Some insurers guarantee renewal while others reserve the right to cancel or modify coverage. Therefore, understanding renewal provisions prevents unexpected coverage gaps.
According to research from the Insurance Information Institute, commercial bicycle couriers face higher accident rates than recreational cyclists, emphasizing the importance of adequate insurance coverage for professional operations.
Claims Process and Support
Efficient claims processing is essential for independent couriers who depend on their equipment for income generation. Providers offering 24/7 claim reporting and rapid response times minimize business disruption. Additionally, advance payment options help couriers replace equipment quickly.
Some insurers provide preferred vendor networks for equipment replacement and repair services. These relationships can expedite repairs and ensure quality workmanship. However, couriers should understand any requirements to use specific vendors or obtain pre-approval for repairs.
Documentation requirements and claim investigation procedures vary between insurers and can affect settlement timelines. Understanding these requirements in advance helps couriers prepare necessary documentation and expedite claim resolution. Therefore, clear communication with insurers improves claim experiences.
Cost Factors and Premium Determination
Individual Risk Assessment
Insurance premiums reflect individual courier risk profiles based on factors including driving history, experience level, and operational practices. New couriers typically face higher premiums due to limited experience and unknown risk patterns. Additionally, accident history and traffic violations affect premium calculations.
Geographic factors significantly influence insurance costs based on local crime rates, traffic density, and weather conditions. Urban areas with high bicycle theft rates or heavy traffic typically result in higher premiums. However, some areas might offer discounts for extensive bike lane networks and cyclist-friendly policies.
Business volume and revenue levels affect commercial insurance pricing since higher activity levels increase exposure to potential claims. Couriers handling high-value cargo or serving premium clients might require additional coverage that increases costs. Therefore, accurate business projections help determine appropriate coverage levels and budgets.
Coverage Level Impacts
Policy limits directly affect premium costs, with higher coverage limits resulting in increased premiums. However, adequate limits are essential for protecting against catastrophic losses that could threaten business viability. Additionally, umbrella policies might provide cost-effective ways to increase overall protection.
Optional coverage endorsements allow couriers to customize policies for specific needs but add to overall costs. Common endorsements include equipment replacement guarantees, business interruption coverage, and enhanced liability limits. Therefore, evaluating the cost-benefit relationship of each endorsement ensures appropriate coverage selection.
Multi-policy discounts might be available for couriers who bundle cargo bike insurance with other coverage types such as general liability or professional indemnity insurance. These discounts can provide significant savings while ensuring comprehensive protection. However, bundling should not compromise coverage quality for cost savings.
Legal Requirements and Compliance
Local and State Regulations
Cargo bike insurance requirements vary significantly between jurisdictions, with some areas requiring specific coverage types or minimum limits. Urban areas might impose stricter requirements than suburban or rural regions. Additionally, courier license requirements might include proof of insurance coverage.
Some jurisdictions classify electric cargo bikes as motor vehicles requiring registration and insurance similar to motorcycles or mopeds. These requirements typically include minimum liability coverage and might exclude certain policy types. Therefore, understanding local regulations prevents legal complications and ensures compliance.
Business licensing requirements often include insurance provisions that indie couriers must satisfy to operate legally. These requirements might specify coverage types, minimum limits, or approved insurer qualifications. However, requirements can change, making ongoing compliance monitoring necessary.
Tax and Business Implications
Insurance premiums for business use are typically tax-deductible as ordinary business expenses. Proper documentation and categorization ensure maximum tax benefits while maintaining compliance with revenue service requirements. Additionally, equipment coverage might affect depreciation calculations for tax purposes.
Business structure decisions affect insurance needs and available coverage options. Sole proprietorships face different requirements than incorporated businesses or partnerships. However, liability protection benefits often favor business incorporation regardless of insurance considerations.
According to Forbes, the gig economy’s growth has created new insurance needs that traditional policies don’t address, making specialized coverage increasingly important for independent contractors.
Safety Practices and Risk Reduction
Equipment Maintenance and Inspection
Regular maintenance schedules reduce equipment failure risks that could result in accidents or cargo damage. Properly maintained brakes, tires, and steering components are essential for safe operations. Additionally, cargo securement systems require regular inspection to prevent load shifting incidents.
Pre-trip inspection procedures help identify potential problems before they cause incidents or breakdowns. These inspections should cover mechanical systems, cargo securement, and safety equipment functionality. However, documented inspection records might provide benefits during insurance claim investigations.
Professional maintenance services ensure that complex systems like electric drive components receive appropriate care. Some insurance policies might require professional maintenance for certain coverage provisions. Therefore, investing in quality maintenance protects both equipment longevity and insurance coverage validity.
Route Planning and Hazard Avoidance
Strategic route planning helps couriers avoid high-risk areas and optimize delivery efficiency. GPS systems and delivery apps often provide real-time traffic and hazard information. Additionally, experienced couriers develop local knowledge about problematic intersections and areas to avoid.
Weather monitoring and contingency planning reduce exposure to dangerous conditions that increase accident risks. Having alternative routes and procedures for severe weather demonstrates professional risk management. However, client communication about weather-related delays prevents service complaints.
Time management practices reduce pressure that might lead to unsafe riding decisions. Realistic scheduling allows for safe navigation and proper cargo handling procedures. Therefore, sustainable business practices align with safety objectives and risk reduction goals.
Technology Integration and Modern Solutions
GPS Tracking and Recovery Systems
Advanced GPS tracking systems provide theft recovery assistance and operational monitoring capabilities. These systems can alert couriers and insurers immediately when unauthorized movement occurs. Additionally, tracking data might provide valuable evidence during insurance claim investigations.
Some insurance providers offer premium discounts for GPS-equipped bikes while others require tracking systems as policy conditions. The investment in tracking technology often pays for itself through insurance savings and theft recovery benefits. However, system reliability and battery life are important considerations.
Real-time location sharing with clients improves service transparency while providing safety benefits through constant position monitoring. Family members or business partners can monitor courier locations for safety purposes. Therefore, tracking technology serves multiple business and safety objectives simultaneously.
Digital Documentation and Claim Management
Mobile apps and digital documentation systems streamline insurance claim reporting and evidence collection. Photo documentation of cargo condition, delivery confirmation, and incident scenes supports insurance claims. Additionally, digital records provide better organization and accessibility than paper systems.
Electronic signature systems and delivery confirmation reduce disputes about service completion and cargo condition. These systems provide timestamp and location data that support courier positions during claim investigations. However, ensuring data security and privacy compliance is essential when handling client information.
Cloud-based backup systems protect critical business documentation from loss due to equipment damage or theft. Insurance claims often require extensive documentation that might be difficult to recreate. Therefore, secure data backup systems provide both operational and insurance benefits.
Conclusion
Cargo bike insurance for independent couriers requires specialized understanding of unique risks, coverage options, and regulatory requirements. The evolving nature of urban delivery services creates new insurance needs that traditional policies don’t address. Additionally, proper coverage selection balances comprehensive protection with cost-effectiveness for sustainable business operations.
Key considerations include distinguishing between personal and commercial coverage needs, understanding cargo bike classifications, and selecting appropriate coverage limits. The claims process, premium factors, and legal compliance requirements all impact insurance decisions. Therefore, indie couriers benefit from working with knowledgeable insurance professionals who understand industry-specific needs.
Success in the cargo bike courier industry depends on managing risks effectively while maintaining operational efficiency. Proper insurance coverage provides financial protection that allows couriers to focus on service delivery and business growth. However, combining adequate insurance with safe operational practices creates the strongest foundation for long-term business success.
Frequently Asked Questions
Do I need commercial insurance if I only do part-time courier work? Yes, most personal bicycle policies exclude business use regardless of frequency. Even part-time courier work requires commercial or hybrid coverage to ensure protection during business activities. Additionally, income loss from accidents affects part-time couriers just as much as full-time operators.
How much does cargo bike insurance typically cost for independent couriers? Insurance costs vary widely based on coverage levels, location, and individual risk factors, but typically range from $500 to $2,000 annually for comprehensive coverage. However, specialized providers might offer more competitive rates than general insurers for courier-specific needs.
Will my electric cargo bike require motorcycle insurance? This depends on your bike’s power output and local regulations. Most pedal-assist e-bikes under 750 watts maintain bicycle classification, but higher-powered or throttle-controlled bikes might require motorcycle-style coverage. Therefore, checking local laws and insurer classifications is essential.
What happens if I’m injured while making deliveries on my cargo bike? Personal injury coverage depends on your specific policy terms and whether you have workers’ compensation or disability insurance. Standard bicycle policies might exclude business-related injuries. Additionally, some courier platforms provide limited injury coverage, but independent contractors typically need separate protection.
Can I get insurance discounts for safety equipment and training? Many insurers offer discounts for GPS tracking systems, professional-grade security equipment, and safety training completion. These discounts reflect reduced risk profiles and often offset equipment costs. However, discount availability and amounts vary between insurance providers.
Read More:
What are the Best Bicycle Brands: Top Picks for Quality Bikes!


